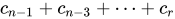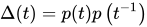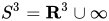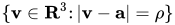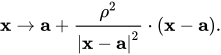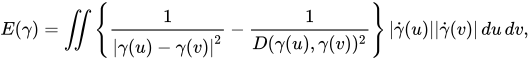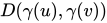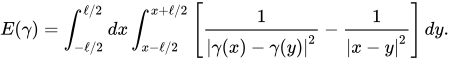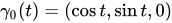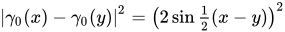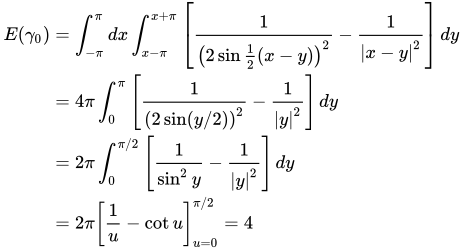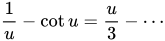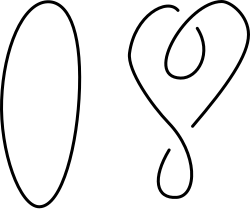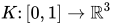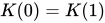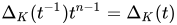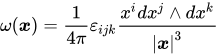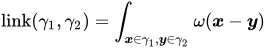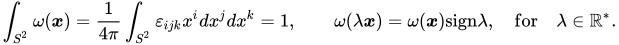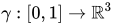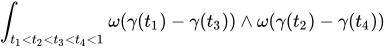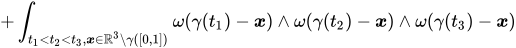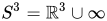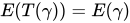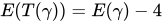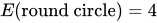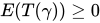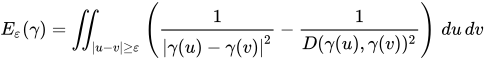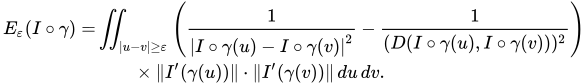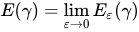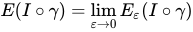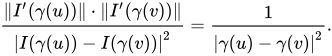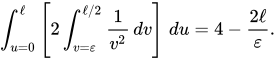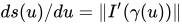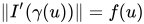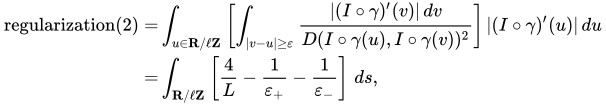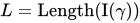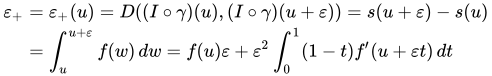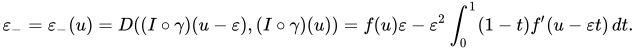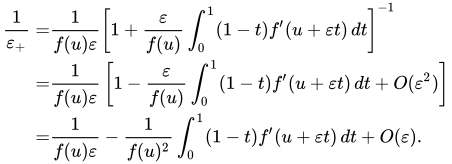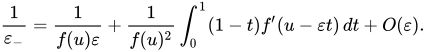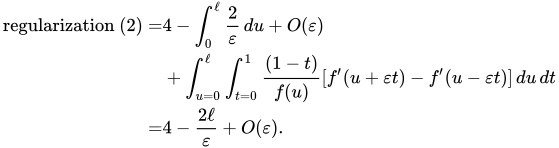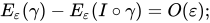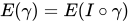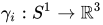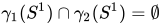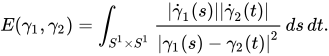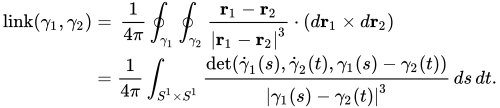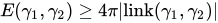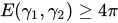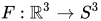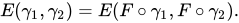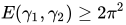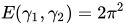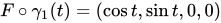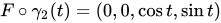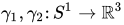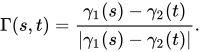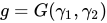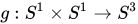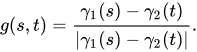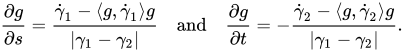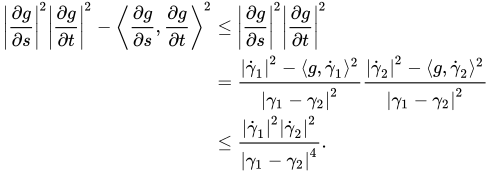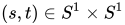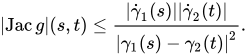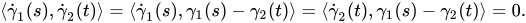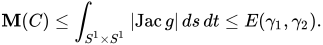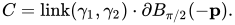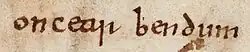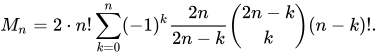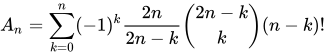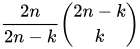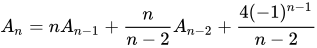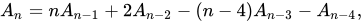Blog

  • Arithmetic topology


    Arithmetic topology is an area of mathematics that is a combination of algebraic number theory and topology. It establishes an analogy between number fields and closed, orientable 3-manifolds.

    Analogies

    The following are some of the analogies used by mathematicians between number fields and 3-manifolds:[1]

    1. A number field corresponds to a closed, orientable 3-manifold
    2. Ideals in the ring of integers correspond to links, and prime ideals correspond to knots.
    3. The field Q of rational numbers corresponds to the 3-sphere.

    Expanding on the last two examples, there is an analogy between knots and prime numbers in which one considers “links” between primes. The triple of primes (13, 61, 937) are “linked” modulo 2 (the Rédei symbol is −1) but are “pairwise unlinked” modulo 2 (the Legendre symbols are all 1). Therefore these primes have been called a “proper Borromean triple modulo 2”[2] or “mod 2 Borromean primes”.[3]

    History

    In the 1960s topological interpretations of class field theory were given by John Tate[4] based on Galois cohomology, and also by Michael Artin and Jean-Louis Verdier[5] based on étale cohomology. Then David Mumford (and independently Yuri Manin) came up with an analogy between prime ideals and knots[6] which was further explored by Barry Mazur.[7][8] In the 1990s Reznikov[9] and Kapranov[10] began studying these analogies, coining the term arithmetic topology for this area of study.

    See also

    • Arithmetic geometry
    • Arithmetic dynamics
    • Topological quantum field theory
    • Langlands program

    Notes

    1. Sikora, Adam S. “Analogies between group actions on 3-manifolds and number fields.” Commentarii Mathematici Helvetici 78.4 (2003): 832-844.
    2. Vogel, Denis (February 13, 2004), Massey products in the Galois cohomology of number fields, doi:10.11588/heidok.00004418, urn:nbn:de:bsz:16-opus-44188
    3. Morishita, Masanori (April 22, 2009), Analogies between Knots and Primes, 3-Manifolds and Number Rings, arXiv:0904.3399, Bibcode:2009arXiv0904.3399M
    4. J. Tate, Duality theorems in Galois cohomology over number fields, (Proc. Intern. Cong. Stockholm, 1962, p. 288-295).
    5. M. Artin and J.-L. Verdier, Seminar on étale cohomology of number fields, Woods Hole Archived May 26, 2011, at the Wayback Machine, 1964.
    6. Who dreamed up the primes=knots analogy? Archived July 18, 2011, at the Wayback Machine, neverendingbooks, lieven le bruyn’s blog, May 16, 2011,
    7. Remarks on the Alexander Polynomial, Barry Mazur, c.1964
    8. B. Mazur, Notes on ´etale cohomology of number fields, Ann. scient. ´Ec. Norm. Sup. 6 (1973), 521-552.
    9. A. Reznikov, Three-manifolds class field theory (Homology of coverings for a nonvirtually b1-positive manifold), Sel. math. New ser. 3, (1997), 361–399.
    10. M. Kapranov, Analogies between the Langlands correspondence and topological quantum field theory, Progress in Math., 131, Birkhäuser, (1995), 119–151.

    Further reading

    External links


    This article is adapted from “Arithmetic topology” on Wikipedia, written by its contributors, and used under CC BY-SA 4.0. Text on this page is available under the same licence. Source snapshot: Wikipedia via Kiwix, 2026-07-20.
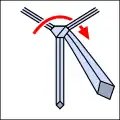
  • Nicky knot

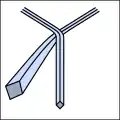
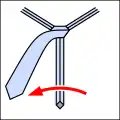
    The Nicky knot is a way of tying a necktie. It is a self-releasing version of the Pratt knot.[1] Like the Pratt knot, it is tied inside-out. It originated in Milan, Italy, and may have been named after Nikita Khrushchev after he visited the city. The knot is larger than the Four-in-hand knot and smaller than the Half-Windsor knot.[2]

    Using the notation of The 85 Ways to Tie a Tie, the Nicky knot is tied

    • Lo Ci Ro Li Co T (knot 4).
    • Nicky knot
    • Nicky knot
    • Nicky knot
    • Nicky knot

    See also

    References

    1. Schmidt, William E. (1989-08-30). “As Neckwear Goes, This Knot’s News”. The New York Times. ISSN 0362-4331. Retrieved 2024-06-04.
    2. Centeno, Antonio (2014-05-22). “How To Tie A Nicky Knot Step By Step with Infographics 2024”. Real Men Real Style. Retrieved 2024-06-04.

    This article is adapted from “Nicky knot” on Wikipedia, written by its contributors, and used under CC BY-SA 4.0. Text on this page is available under the same licence. Source snapshot: Wikipedia via Kiwix, 2026-07-20.
  • Arf invariant of a knot

    In the mathematical field of knot theory, the Arf invariant of a knot, named after Cahit Arf, is a knot invariant obtained from a quadratic form associated to a Seifert surface. If F is a Seifert surface of a knot, then the homology group H1(F, Z/2Z) has a quadratic form whose value is the number of full twists mod 2 in a neighborhood of an embedded circle representing an element of the homology group. The Arf invariant of this quadratic form is the Arf invariant of the knot.

    Definition by Seifert matrix

    Let V = v i , j {\displaystyle V=v_{i,j}} {\displaystyle V=v_{i,j}} be a Seifert matrix of the knot, constructed from a set of curves on a Seifert surface of genus g which represent a basis for the first homology of the surface. This means that V is a 2g × 2g matrix with the property that VVT is a symplectic matrix. The Arf invariant of the knot is the residue of

    i = 1 g v 2 i 1 , 2 i 1 v 2 i , 2 i ( mod 2 ) . {\displaystyle \sum \limits _{i=1}^{g}v_{2i-1,2i-1}v_{2i,2i}{\pmod {2}}.} {\displaystyle \sum \limits _{i=1}^{g}v_{2i-1,2i-1}v_{2i,2i}{\pmod {2}}.}

    Specifically, if { a i , b i } , i = 1 g {\displaystyle \{a_{i},b_{i}\},i=1\ldots g} {\displaystyle \{a_{i},b_{i}\},i=1\ldots g}, is a symplectic basis for the intersection form on the Seifert surface, then

    Arf ( K ) = i = 1 g lk ( a i , a i + ) lk ( b i , b i + ) ( mod 2 ) . {\displaystyle \operatorname {Arf} (K)=\sum \limits _{i=1}^{g}\operatorname {lk} \left(a_{i},a_{i}^{+}\right)\operatorname {lk} \left(b_{i},b_{i}^{+}\right){\pmod {2}}.} {\displaystyle \operatorname {Arf} (K)=\sum \limits _{i=1}^{g}\operatorname {lk} \left(a_{i},a_{i}^{+}\right)\operatorname {lk} \left(b_{i},b_{i}^{+}\right){\pmod {2}}.}

    where lk is the link number and a + {\displaystyle a^{+}} {\displaystyle a^{+}} denotes the positive pushoff of a.

    Definition by pass equivalence

    This approach to the Arf invariant is due to Louis Kauffman.

    We define two knots to be pass equivalent if they are related by a finite sequence of pass-moves.[1]

    Every knot is pass-equivalent to either the unknot or the trefoil; these two knots are not pass-equivalent and additionally, the right- and left-handed trefoils are pass-equivalent.[2]

    Now we can define the Arf invariant of a knot to be 0 if it is pass-equivalent to the unknot, or 1 if it is pass-equivalent to the trefoil. This definition is equivalent to the one above.

    Definition by partition function

    Vaughan Jones showed that the Arf invariant can be obtained by taking the partition function of an Ising model on a knot diagram.[3]

    Definition by Alexander polynomial

    This approach to the Arf invariant is by Raymond Robertello.[4] Let

    Δ ( t ) = c 0 + c 1 t + + c n t n + + c 0 t 2 n {\displaystyle \Delta (t)=c_{0}+c_{1}t+\cdots +c_{n}t^{n}+\cdots +c_{0}t^{2n}} {\displaystyle \Delta (t)=c_{0}+c_{1}t+\cdots +c_{n}t^{n}+\cdots +c_{0}t^{2n}}

    be the Alexander polynomial of the knot. Then the Arf invariant is the residue of

    c n 1 + c n 3 + + c r {\displaystyle c_{n-1}+c_{n-3}+\cdots +c_{r}} {\displaystyle c_{n-1}+c_{n-3}+\cdots +c_{r}}

    modulo 2, where r = 0 for n odd, and r = 1 for n even.

    Kunio Murasugi[5] proved that the Arf invariant is zero if and only if Δ(−1) ≡ ±1 modulo 8.

    Arf as knot concordance invariant

    From the Fox-Milnor criterion, which tells us that the Alexander polynomial of a slice knot K S 3 {\displaystyle K\subset \mathbb {S} ^{3}} {\displaystyle K\subset \mathbb {S} ^{3}} factors as Δ ( t ) = p ( t ) p ( t 1 ) {\displaystyle \Delta (t)=p(t)p\left(t^{-1}\right)} {\displaystyle \Delta (t)=p(t)p\left(t^{-1}\right)} for some polynomial p ( t ) {\displaystyle p(t)} {\displaystyle p(t)} with integer coefficients, we know that the determinant | Δ ( 1 ) | {\displaystyle \left|\Delta (-1)\right|} {\displaystyle \left|\Delta (-1)\right|} of a slice knot is a square integer. As | Δ ( 1 ) | {\displaystyle \left|\Delta (-1)\right|} {\displaystyle \left|\Delta (-1)\right|} is an odd integer, it has to be congruent to 1 modulo 8. Combined with Murasugi’s result, this shows that the Arf invariant of a slice knot vanishes.

    Notes

    1. Kauffman (1987) p.74
    2. Kauffman (1987) pp.75–78
    3. Jones, Vaughan F. R. (1990), “Knot theory and statistical mechanics”, Scientific American, 263 (5): 4, 98–103, doi:10.1038/scientificamerican1190-98, JSTOR 24996978, MR 1079724
    4. Robertello, Raymond, An Invariant of Knot Corbordism, Communications on Pure and Applied Mathematics, Volume 18, pp. 543555, 1965
    5. Murasugi, Kunio, The Arf Invariant for Knot Types, Proceedings of the American Mathematical Society, Vol. 21, No. 1. (Apr., 1969), pp. 6972

    References

    • Kauffman, Louis H. (1983). Formal knot theory. Mathematical notes. Vol. 30. Princeton University Press. ISBN 0-691-08336-3.
    • Kauffman, Louis H. (1987). On knots. Annals of Mathematics Studies. Vol. 115. Princeton University Press. ISBN 0-691-08435-1.
    • Kirby, Robion (1989). The topology of 4-manifolds. Lecture Notes in Mathematics. Vol. 1374. Springer-Verlag. ISBN 0-387-51148-2.


    This article is adapted from “Arf invariant of a knot” on Wikipedia, written by its contributors, and used under CC BY-SA 4.0. Text on this page is available under the same licence. Source snapshot: Wikipedia via Kiwix, 2026-07-20.
  • Nail knot

    Nail knot
    Nail knot
    Category Bend
    Typical use fly fishing

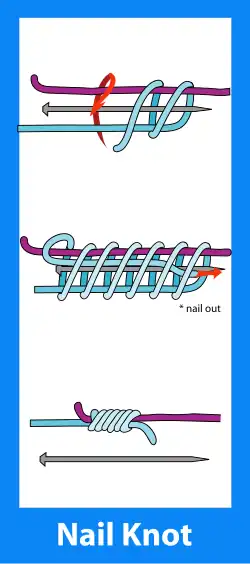
    The nail knot, also known as the tube knot or gryp knot, is used in fly fishing to attach the leader to the main fishing line. The knot has been described as “The best known knot for tying a
    permanent leader butt of monofilament to a fly line”[1] and “the most satisfactory means of attaching a leader butt to a fly line.”
    [2] Fly fishing author Sheridan Anderson recommended coating the nail knot with rubberized glue to prevent the knot from hanging up on the guides of the fishing pole.[3]

    The nail knot got its name because a nail or similar object such as a narrow straw is inserted as a guide when tying the knot. To tie the nail knot by hand is widely described as very difficult; therefore some anglers use a nail knot-tying tool. Such a tool can be fashioned from a partially straightened paper clip.[1] Commercial versions of nail knot tools are also available. One example is made by Tie-Fast.[4]

    See also

    References

    1. 1 2 “Tying the instant nail knot”. Field & Stream. April 1974. pp. 124, 134. Retrieved February 26, 2025.
    2. Blaisdell, Harold F. (August 1974). “Another Man’s Version of the Instant Nail Knot”. Field & Stream. p. 72. Retrieved February 26, 2025.
    3. Anderson, Sheridan (1978). The Curtis Creek Manifesto. Frank Amato Publications. p. 29. ISBN 9780936608068.
    4. Baldwin, Ken (December 12, 2024). “Inexpensive Holiday Gifts for Fly Fishing That Give Big Returns: Looking for the perfect fly fishing stocking stuffers? Check out these affordable and useful gifts that any angler will love”. Sports Illustrated. Retrieved February 26, 2025.

    External links


    This article is adapted from “Nail knot” on Wikipedia, written by its contributors, and used under CC BY-SA 4.0. Text on this page is available under the same licence. Source snapshot: Wikipedia via Kiwix, 2026-07-20.

  • Arbor knot

    Arbor knot
    Arbor knot
    Names Arbor knot, Canadian jam knot
    Category Hitch
    Related Honda knot, Noose, Slip knot
    Typical use Fishing
    ABoK #190, #1114

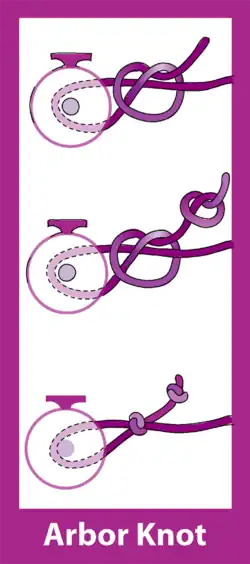
    The Arbor knot is a typical fishers’ knot. Its primary use is to attach fishing line to the arbor of a fishing reel.

    It has also gained popularity (often under the name “Canadian Jam Knot” or nicknamed “bushcraft zip tie”) as a general binding knot to tie down a roll of e.g. a sleeping bag, or to begin a lashing.[1]

    Tying

    An arbor knot is tied by first passing the line around the reel arbor. The tag end is then tied in an overhand knot around the running line. Finally, an overhand knot is tied in the tag end. When tightened, the overhand knot in the tag end jams against the overhand knot tied around the running line.[2]

    See also

    References

    1. McCoy, Matthew (2021). Knot Tying for Beginners. (independently published). ISBN 979-8468156971.
    2. Gene Kugach (1993). Fishing Basics: The Complete Illustrated Guide. Stackpole Books. ISBN 0-8117-3001-8.

    External links


    This article is adapted from “Arbor knot” on Wikipedia, written by its contributors, and used under CC BY-SA 4.0. Text on this page is available under the same licence. Source snapshot: Wikipedia via Kiwix, 2026-07-20.
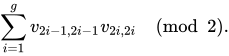
  • Angler’s loop

    Angler’s loop
    Angler's loop
    Names Angler’s loop, Perfection loop
    Category Loop
    Releasing Jamming
    Typical use Fishing, forming a fixed loop in bungee cord
    ABoK #1017, #1035, #2067
    Instructions

    An angler’s loop, otherwise known as a perfection loop, is a type of knot which forms a fixed loop. Useful for fine or slippery line, it is one of the few loop knots which holds well in bungee cord. It is quite secure, but it jams badly and is not suitable if the knot will need to be untied. [1]

    Tying

    Angler’s loop may be tied

    • alone and then used,
      • it may be tied in the bight or at the working end
      • it may be tied one handed
      • it may be fashioned with several loops
      • it may be locked for additional stability
      • it may be tied at high speed in an emergency
    • it may be tied through an object (typically a ring).
    Angler's loop
    Untightened angler’s loop
    Angler's loop
    Method of tying the angler’s loop through an object
    • Start with a loop near the working end
      Start with a loop near the working end
    • Continue with two loops around standing end
      Continue with two loops around standing end
    • one large and one small in the middle
      one large and one small in the middle
    • Pull the large loop over the small (working end) and through the first loop
      Pull the large loop over the small (working end) and through the first loop
    • Tighten pulling in all three directions.
      Tighten pulling in all three directions.

    Angler’s loop may be tied around the hand, it may also be tied this way one handed, or with several loops if need be:

    • Hold the working end, loop the standing end 3 times around the palm
      Hold the working end, loop the standing end 3 times around the palm
    • Pull the outmost loop inwards under the first two
      Pull the outmost loop inwards under the first two
    • Pull the next outmost over the one(s) in the middle and under the now innermost loop
      Pull the next outmost over the one(s) in the middle and under the now innermost loop
    • Pull the now innermost loop(s) and the standing end to tighten.
      Pull the now innermost loop(s) and the standing end to tighten.
    • Done.
      Done.
    • Angler’s loop may be locked additionally with half hitches
    Angler's loop
    Locked simple loop A half hitch around the loops root locks it
    • Angler’s loop may be fashioned with several loops (then locking may be necessary)
    Angler's loop
    with several loops and locked first the loops in desired size, last loop is for the knot and may be smaller. half hitches around the loops roots locks them.
    • A version with an additional locking turn of the tail called Double Dragon is shown in this video:

    youtube.com/watch?v=gWhLCM3Hm7U

    Structure

    Overhand knot on standing part and half-hitch by the working end.

    See also

    References

    1. “Anglers loop or Perfection loop”. Knots and Climbing. 2025. Retrieved 13 May 2025.{{cite web}}: CS1 maint: deprecated archival service (link)
    • Budworth, Geoffrey (2012). The Knot Book Hachette UK. ISBN 9780716023159.
    • Toss, Brion and Gae Pilon (2009). Chapman Knots for Boaters, pages 68–68, Sterling Publishing Company. ISBN 9781588167781.

    External links


    This article is adapted from “Angler's loop” on Wikipedia, written by its contributors, and used under CC BY-SA 4.0. Text on this page is available under the same licence. Source snapshot: Wikipedia via Kiwix, 2026-07-20.
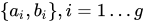
  • Möbius energy


    In mathematics, the Möbius energy of a knot is a particular knot energy, i.e., a functional on the space of knots. It was discovered by Jun O’Hara, who demonstrated that the energy blows up as the knot’s strands get close to one another.[1] This is a useful property because it prevents self-intersection and ensures the result under gradient descent is of the same knot type.

    Möbius energy
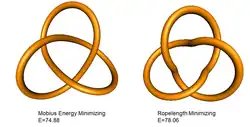
    Pictures of two trefoil knots, with different Möbius energies. The knot on the left has a Möbius energy of 74.88, close to the minimum of 74.41 [2]. The knot on the right has close to the minimum ropelength, but a higher Möbius energy of 78.06.

    Invariance of Möbius energy under Möbius transformations was demonstrated by Michael Freedman, Zheng-Xu He, and Zhenghan Wang (1994) who used it to show the existence of a C 1 , 1 {\displaystyle C^{1,1}} {\displaystyle C^{1,1}} energy minimizer in each isotopy class of a prime knot. They also showed the minimum energy of any knot conformation is achieved by a round circle.[3]

    Conjecturally, there is no energy minimizer for composite knots. Robert B. Kusner and John M. Sullivan have done computer experiments with a discretized version of the Möbius energy and concluded that there should be no energy minimizer for the knot sum of two trefoils (although this is not a proof).

    Recall that the Möbius transformations of the 3-sphere
    S 3 = R 3 {\displaystyle S^{3}=\mathbf {R} ^{3}\cup \infty } {\displaystyle S^{3}=\mathbf {R} ^{3}\cup \infty } are the ten-dimensional group of angle-preserving diffeomorphisms generated by inversion in 2-spheres. For example, the inversion in the sphere { v R 3 : | v a | = ρ } {\displaystyle \{\mathbf {v} \in \mathbf {R} ^{3}\colon |\mathbf {v} -\mathbf {a} |=\rho \}} {\displaystyle \{\mathbf {v} \in \mathbf {R} ^{3}\colon |\mathbf {v} -\mathbf {a} |=\rho \}} is defined by
    x a + ρ 2 | x a | 2 ( x a ) . {\displaystyle \mathbf {x} \to \mathbf {a} +{\rho ^{2} \over |\mathbf {x} -\mathbf {a} |^{2}}\cdot (\mathbf {x} -\mathbf {a} ).} {\displaystyle \mathbf {x} \to \mathbf {a} +{\rho ^{2} \over |\mathbf {x} -\mathbf {a} |^{2}}\cdot (\mathbf {x} -\mathbf {a} ).}

    Consider a rectifiable simple curve γ ( u ) {\displaystyle \gamma (u)} {\displaystyle \gamma (u)} in the Euclidean
    3-space R 3 {\displaystyle \mathbf {R} ^{3}} {\displaystyle \mathbf {R} ^{3}}, where u {\displaystyle u} {\displaystyle u} belongs to R 1 {\displaystyle \mathbf {R} ^{1}} {\displaystyle \mathbf {R} ^{1}} or S 1 {\displaystyle S^{1}} {\displaystyle S^{1}}. Define its energy by

    E ( γ ) = { 1 | γ ( u ) γ ( v ) | 2 1 D ( γ ( u ) , γ ( v ) ) 2 } | γ ˙ ( u ) | | γ ˙ ( v ) | d u d v , {\displaystyle E(\gamma )=\iint \left\{{\frac {1}{|\gamma (u)-\gamma (v)|^{2}}}-{\frac {1}{D(\gamma (u),\gamma (v))^{2}}}\right\}|{\dot {\gamma }}(u)||{\dot {\gamma }}(v)|\,du\,dv,} {\displaystyle E(\gamma )=\iint \left\{{\frac {1}{|\gamma (u)-\gamma (v)|^{2}}}-{\frac {1}{D(\gamma (u),\gamma (v))^{2}}}\right\}|{\dot {\gamma }}(u)||{\dot {\gamma }}(v)|\,du\,dv,}

    where D ( γ ( u ) , γ ( v ) ) {\displaystyle D(\gamma (u),\gamma (v))} {\displaystyle D(\gamma (u),\gamma (v))} is the shortest arc
    distance between γ ( u ) {\displaystyle \gamma (u)} {\displaystyle \gamma (u)}
    and γ ( v ) {\displaystyle \gamma (v)} {\displaystyle \gamma (v)} on the curve. The second term of the
    integrand is called a
    regularization. It is easy to see that E ( γ ) {\displaystyle E(\gamma )} {\displaystyle E(\gamma )} is
    independent of parametrization and is unchanged if γ {\displaystyle \gamma } {\displaystyle \gamma } is changed by a similarity of R 3 {\displaystyle \mathbf {R} ^{3}} {\displaystyle \mathbf {R} ^{3}}. Moreover, the energy of any line is 0, the energy of any circle is 4 {\displaystyle 4} {\displaystyle 4}. In fact, let us use the arc-length parameterization. Denote by {\displaystyle \ell } {\displaystyle \ell } the length of the curve γ {\displaystyle \gamma } {\displaystyle \gamma }. Then

    E ( γ ) = / 2 / 2 d x x / 2 x + / 2 [ 1 | γ ( x ) γ ( y ) | 2 1 | x y | 2 ] d y . {\displaystyle E(\gamma )=\int _{-\ell /2}^{\ell /2}{}dx\int _{x-\ell /2}^{x+\ell /2}\left[{1 \over |\gamma (x)-\gamma (y)|^{2}}-{1 \over |x-y|^{2}}\right]dy.} {\displaystyle E(\gamma )=\int _{-\ell /2}^{\ell /2}{}dx\int _{x-\ell /2}^{x+\ell /2}\left[{1 \over |\gamma (x)-\gamma (y)|^{2}}-{1 \over |x-y|^{2}}\right]dy.}

    Let γ 0 ( t ) = ( cos t , sin t , 0 ) {\displaystyle \gamma _{0}(t)=(\cos t,\sin t,0)} {\displaystyle \gamma _{0}(t)=(\cos t,\sin t,0)} denote a unit circle. We have

    | γ 0 ( x ) γ 0 ( y ) | 2 = ( 2 sin 1 2 ( x y ) ) 2 {\displaystyle |\gamma _{0}(x)-\gamma _{0}(y)|^{2}={\left(2\sin {\tfrac {1}{2}}(x-y)\right)^{2}}} {\displaystyle |\gamma _{0}(x)-\gamma _{0}(y)|^{2}={\left(2\sin {\tfrac {1}{2}}(x-y)\right)^{2}}}

    and consequently,

    E ( γ 0 ) = π π d x x π x + π [ 1 ( 2 sin 1 2 ( x y ) ) 2 1 | x y | 2 ] d y = 4 π 0 π [ 1 ( 2 sin ( y / 2 ) ) 2 1 | y | 2 ] d y = 2 π 0 π / 2 [ 1 sin 2 y 1 | y | 2 ] d y = 2 π [ 1 u cot u ] u = 0 π / 2 = 4 {\displaystyle {\begin{aligned}E(\gamma _{0})&=\int _{-\pi }^{\pi }{}dx\int _{x-\pi }^{x+\pi }\left[{1 \over \left(2\sin {\tfrac {1}{2}}(x-y)\right)^{2}}-{1 \over |x-y|^{2}}\right]dy\\&=4\pi \int _{0}^{\pi }\left[{1 \over \left(2\sin(y/2)\right)^{2}}-{1 \over |y|^{2}}\right]dy\\&=2\pi \int _{0}^{\pi /2}\left[{1 \over \sin ^{2}y}-{1 \over |y|^{2}}\right]dy\\&=2\pi \left[{1 \over u}-\cot u\right]_{u=0}^{\pi /2}=4\end{aligned}}} {\displaystyle {\begin{aligned}E(\gamma _{0})&=\int _{-\pi }^{\pi }{}dx\int _{x-\pi }^{x+\pi }\left[{1 \over \left(2\sin {\tfrac {1}{2}}(x-y)\right)^{2}}-{1 \over |x-y|^{2}}\right]dy\\&=4\pi \int _{0}^{\pi }\left[{1 \over \left(2\sin(y/2)\right)^{2}}-{1 \over |y|^{2}}\right]dy\\&=2\pi \int _{0}^{\pi /2}\left[{1 \over \sin ^{2}y}-{1 \over |y|^{2}}\right]dy\\&=2\pi \left[{1 \over u}-\cot u\right]_{u=0}^{\pi /2}=4\end{aligned}}}

    since 1 u cot u = u 3 {\displaystyle {\frac {1}{u}}-\cot u={\frac {u}{3}}-\cdots } {\displaystyle {\frac {1}{u}}-\cot u={\frac {u}{3}}-\cdots }.

    Knot invariant

    Möbius energy
    Möbius energy
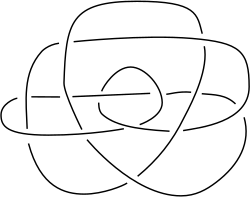
    On the left, the unknot, and a knot equivalent to it. It can be more difficult to determine whether complex knots, such as the one on the right, are equivalent to the unknot.

    A knot is created by beginning with a one-dimensional line segment, wrapping it around itself arbitrarily, and then fusing its two free ends together to form a closed loop.[4] Mathematically, we can say a knot K {\displaystyle K} {\displaystyle K} is an injective and continuous function K : [ 0 , 1 ] R 3 {\displaystyle K\colon [0,1]\to \mathbb {R} ^{3}} {\displaystyle K\colon [0,1]\to \mathbb {R} ^{3}} with K ( 0 ) = K ( 1 ) {\displaystyle K(0)=K(1)} {\displaystyle K(0)=K(1)}. Topologists consider knots and other entanglements such as links and braids to be equivalent if the knot can be pushed about smoothly, without intersecting itself, to coincide with another knot. The idea of knot equivalence is to give a precise definition of when two knots should be considered the same even when positioned quite differently in space. A mathematical definition is that two knots K 1 , K 2 {\displaystyle K_{1},K_{2}} {\displaystyle K_{1},K_{2}} are equivalent if there is an orientation-preserving homeomorphism h : R 3 R 3 {\displaystyle h\colon \mathbb {R} ^{3}\to \mathbb {R} ^{3}} {\displaystyle h\colon \mathbb {R} ^{3}\to \mathbb {R} ^{3}} with h ( K 1 ) = K 2 {\displaystyle h(K_{1})=K_{2}} {\displaystyle h(K_{1})=K_{2}}, and this is known to be equivalent to existence of ambient isotopy.

    The basic problem of knot theory, the recognition problem, is determining the equivalence of two knots. Algorithms exist to solve this problem, with the first given by Wolfgang Haken in the late 1960s.[5] Nonetheless, these algorithms can be extremely time-consuming, and a major issue in the theory is to understand how hard this problem really is.[5] The special case of recognizing the unknot, called the unknotting problem, is of particular interest.[6]
    We shall picture a knot by a smooth curve rather than by a polygon. A knot will be represented by a planar diagram. The singularities of the planar diagram will be called crossing points and the regions into which it subdivides the plane regions of the diagram. At each crossing point, two of the four corners will be dotted to indicate which branch through the crossing point is to be thought of as one passing under the other. We number any one region at random, but shall fix the numbers of all remaining regions such that whenever we cross the curve from right to left we must pass from region number k {\displaystyle k} {\displaystyle k} to the region number k + 1 {\displaystyle k+1} {\displaystyle k+1}. Clearly, at any crossing point c {\displaystyle c} {\displaystyle c}, there are two opposite corners of the same number k {\displaystyle k} {\displaystyle k} and two opposite corners of the numbers k 1 {\displaystyle k-1} {\displaystyle k-1} and k + 1 {\displaystyle k+1} {\displaystyle k+1}, respectively. The number k {\displaystyle k} {\displaystyle k} is referred as the index of c {\displaystyle c} {\displaystyle c}. The crossing points are distinguished by two types: the right handed and the left handed, according to which branch through the point passes under or behind the other. At any crossing point of index k {\displaystyle k} {\displaystyle k} two dotted corners are of numbers k {\displaystyle k} {\displaystyle k} and k + 1 {\displaystyle k+1} {\displaystyle k+1}, respectively, two undotted ones of numbers k 1 {\displaystyle k-1} {\displaystyle k-1} and k + 1 {\displaystyle k+1} {\displaystyle k+1}. The index of any corner of any region of index k {\displaystyle k} {\displaystyle k} is one element of { k ± 1 , k } {\displaystyle \{k\pm 1,k\}} {\displaystyle \{k\pm 1,k\}}. We wish to distinguish one type of knot from another by knot invariants. There is one invariant which is quite simple. It is Alexander polynomial Δ K ( t ) {\displaystyle \Delta _{K}(t)} {\displaystyle \Delta _{K}(t)} with integer coefficient. The Alexander polynomial is symmetric with degree n {\displaystyle n} {\displaystyle n}: Δ K ( t 1 ) t n 1 = Δ K ( t ) {\displaystyle \Delta _{K}(t^{-1})t^{n-1}=\Delta _{K}(t)} {\displaystyle \Delta _{K}(t^{-1})t^{n-1}=\Delta _{K}(t)} for all knots K {\displaystyle K} {\displaystyle K} of n > 0 {\displaystyle n>0} {\displaystyle n>0} crossing points. For example, the invariant Δ K ( t ) {\displaystyle \Delta _{K}(t)} {\displaystyle \Delta _{K}(t)} of an unknotted curve is 1, of an trefoil knot is t 2 t + 1 {\displaystyle t^{2}-t+1} {\displaystyle t^{2}-t+1}.

    • The left handed trefoil knot.
      The left handed trefoil knot.
    • The right handed trefoil knot.
      The right handed trefoil knot.

    Let

    ω ( x ) = 1 4 π ε i j k x i d x j d x k | x | 3 {\displaystyle \omega ({\boldsymbol {x}})={\frac {1}{4\pi }}\varepsilon _{ijk}{x^{i}dx^{j}\wedge dx^{k} \over |{\boldsymbol {x}}|^{3}}} {\displaystyle \omega ({\boldsymbol {x}})={\frac {1}{4\pi }}\varepsilon _{ijk}{x^{i}dx^{j}\wedge dx^{k} \over |{\boldsymbol {x}}|^{3}}} denote the standard surface element of S 2 {\displaystyle S^{2}} {\displaystyle S^{2}}.

    We have

    l i n k ( γ 1 , γ 2 ) = x γ 1 , y γ 2 ω ( x y ) {\displaystyle \mathrm {link} (\gamma _{1},\gamma _{2})=\int _{{\boldsymbol {x}}\in \gamma _{1},{\boldsymbol {y}}\in \gamma _{2}}\omega ({\boldsymbol {x}}-{\boldsymbol {y}})} {\displaystyle \mathrm {link} (\gamma _{1},\gamma _{2})=\int _{{\boldsymbol {x}}\in \gamma _{1},{\boldsymbol {y}}\in \gamma _{2}}\omega ({\boldsymbol {x}}-{\boldsymbol {y}})}
    S 2 ω ( x ) = 1 4 π S 2 ε i j k x i d x j d x k = 1 , ω ( λ x ) = ω ( x ) s i g n λ , f o r λ R . {\displaystyle \int _{S^{2}}\omega ({\boldsymbol {x}})={\frac {1}{4\pi }}\int _{S^{2}}\varepsilon _{ijk}x^{i}dx^{j}dx^{k}=1,\qquad \omega (\lambda {\boldsymbol {x}})=\omega ({\boldsymbol {x}}){\rm {sign}}\lambda ,\quad {\rm {for}}\quad \lambda \in \mathbb {R} ^{*}.} {\displaystyle \int _{S^{2}}\omega ({\boldsymbol {x}})={\frac {1}{4\pi }}\int _{S^{2}}\varepsilon _{ijk}x^{i}dx^{j}dx^{k}=1,\qquad \omega (\lambda {\boldsymbol {x}})=\omega ({\boldsymbol {x}}){\rm {sign}}\lambda ,\quad {\rm {for}}\quad \lambda \in \mathbb {R} ^{*}.}

    For the knot γ : [ 0 , 1 ] R 3 {\displaystyle \gamma :[0,1]\rightarrow \mathbb {R} ^{3}}

    {\displaystyle \gamma :[0,1]\rightarrow \mathbb {R} ^{3}}, γ ( 0 ) = γ ( 1 ) {\displaystyle \gamma (0)=\gamma (1)} {\displaystyle \gamma (0)=\gamma (1)},

    t 1 < t 2 < t 3 < t 4 < 1 ω ( γ ( t 1 ) γ ( t 3 ) ) ω ( γ ( t 2 ) γ ( t 4 ) ) {\displaystyle \int _{t_{1}<t_{2}<t_{3}<t_{4}<1}\omega (\gamma (t_{1})-\gamma (t_{3}))\wedge \omega (\gamma (t_{2})-\gamma (t_{4}))} {\displaystyle \int _{t_{1}<t_{2}<t_{3}<t_{4}<1}\omega (\gamma (t_{1})-\gamma (t_{3}))\wedge \omega (\gamma (t_{2})-\gamma (t_{4}))}
    + t 1 < t 2 < t 3 , x R 3 γ ( [ 0 , 1 ] ) ω ( γ ( t 1 ) x ) ω ( γ ( t 2 ) x ) ω ( γ ( t 3 ) x ) {\displaystyle +\int _{t_{1}<t_{2}<t_{3},{\boldsymbol {x}}\in \mathbb {R} ^{3}\setminus \gamma ([0,1])}\omega (\gamma (t_{1})-{\boldsymbol {x}})\wedge \omega (\gamma (t_{2})-{\boldsymbol {x}})\wedge \omega (\gamma (t_{3})-{\boldsymbol {x}})} {\displaystyle +\int _{t_{1}<t_{2}<t_{3},{\boldsymbol {x}}\in \mathbb {R} ^{3}\setminus \gamma ([0,1])}\omega (\gamma (t_{1})-{\boldsymbol {x}})\wedge \omega (\gamma (t_{2})-{\boldsymbol {x}})\wedge \omega (\gamma (t_{3})-{\boldsymbol {x}})}

    does not change, if we change the knot γ {\displaystyle \gamma } {\displaystyle \gamma } in its equivalence class.

    Möbius Invariance Property

    Let γ {\displaystyle \gamma } {\displaystyle \gamma } be a closed curve in R 3 {\displaystyle \mathbb {R} ^{3}} {\displaystyle \mathbb {R} ^{3}} and T {\displaystyle T} {\displaystyle T} a Möbius transformation of S 3 = R 3 {\displaystyle S^{3}=\mathbb {R} ^{3}\cup \infty } {\displaystyle S^{3}=\mathbb {R} ^{3}\cup \infty }. If T ( γ ) {\displaystyle T(\gamma )} {\displaystyle T(\gamma )} is contained in R 3 {\displaystyle \mathbb {R} ^{3}} {\displaystyle \mathbb {R} ^{3}} then E ( T ( γ ) ) = E ( γ ) {\displaystyle E(T(\gamma ))=E(\gamma )} {\displaystyle E(T(\gamma ))=E(\gamma )}. If T ( γ ) {\displaystyle T(\gamma )} {\displaystyle T(\gamma )} passes through {\displaystyle \infty } {\displaystyle \infty } then E ( T ( γ ) ) = E ( γ ) 4 {\displaystyle E(T(\gamma ))=E(\gamma )-4} {\displaystyle E(T(\gamma ))=E(\gamma )-4}.

    Theorem A. Among all rectifiable loops γ : S 1 R 3 {\displaystyle \gamma \colon S^{1}\to \mathbb {R} ^{3}} {\displaystyle \gamma \colon S^{1}\to \mathbb {R} ^{3}}, round circles have the least energy E ( round circle ) = 4 {\displaystyle E({\text{round circle}})=4} {\displaystyle E({\text{round circle}})=4} and any γ {\displaystyle \gamma } {\displaystyle \gamma } of least energy parameterizes a round circle.

    Proof of Theorem A. Let T {\displaystyle T} {\displaystyle T} be a Möbius transformation sending a point of γ {\displaystyle \gamma } {\displaystyle \gamma } to infinity. The energy E ( T ( γ ) ) 0 {\displaystyle E(T(\gamma ))\geq 0} {\displaystyle E(T(\gamma ))\geq 0} with equality holding if and only if T ( γ ) {\displaystyle T(\gamma )} {\displaystyle T(\gamma )} is a straight line. Apply the Möbius invariance property we complete the proof.

    Proof of Möbius Invariance Property. It is sufficient to consider how I {\displaystyle I} {\displaystyle I}, an inversion in a sphere, transforms energy. Let u {\displaystyle u} {\displaystyle u} be the arc length parameter of a rectifiable closed curve γ {\displaystyle \gamma } {\displaystyle \gamma }, u R / Z {\displaystyle u\in \mathbb {R} /\ell \mathbb {Z} } {\displaystyle u\in \mathbb {R} /\ell \mathbb {Z} }. Let

    E ε ( γ ) = | u v | ε ( 1 | γ ( u ) γ ( v ) | 2 1 D ( γ ( u ) , γ ( v ) ) 2 ) d u d v {\displaystyle E_{\varepsilon }(\gamma )=\iint _{|u-v|\geq \varepsilon }\left({\frac {1}{|\gamma (u)-\gamma (v)|^{2}}}-{\frac {1}{D(\gamma (u),\gamma (v))^{2}}}\right)\,du\,dv} {\displaystyle E_{\varepsilon }(\gamma )=\iint _{|u-v|\geq \varepsilon }\left({\frac {1}{|\gamma (u)-\gamma (v)|^{2}}}-{\frac {1}{D(\gamma (u),\gamma (v))^{2}}}\right)\,du\,dv} 1

    and

    E ε ( I γ ) = | u v | ε ( 1 | I γ ( u ) I γ ( v ) | 2 1 ( D ( I γ ( u ) , I γ ( v ) ) ) 2 ) × I ( γ ( u ) ) I ( γ ( v ) ) d u d v . {\displaystyle {\begin{aligned}E_{\varepsilon }(I\circ \gamma )=&\iint _{|u-v|\geq \varepsilon }\left({\frac {1}{|I\circ \gamma (u)-I\circ \gamma (v)|^{2}}}-{\frac {1}{(D(I\circ \gamma (u),I\circ \gamma (v)))^{2}}}\right)\\&\qquad \times \|I'(\gamma (u))\|\cdot \|I'(\gamma (v))\|\,du\,dv.\end{aligned}}} {\displaystyle {\begin{aligned}E_{\varepsilon }(I\circ \gamma )=&\iint _{|u-v|\geq \varepsilon }\left({\frac {1}{|I\circ \gamma (u)-I\circ \gamma (v)|^{2}}}-{\frac {1}{(D(I\circ \gamma (u),I\circ \gamma (v)))^{2}}}\right)\\&\qquad \times \|I'(\gamma (u))\|\cdot \|I'(\gamma (v))\|\,du\,dv.\end{aligned}}} 2

    Clearly, E ( γ ) = lim ε 0 E ε ( γ ) {\displaystyle E(\gamma )=\lim _{\varepsilon \to 0}E_{\varepsilon }(\gamma )} {\displaystyle E(\gamma )=\lim _{\varepsilon \to 0}E_{\varepsilon }(\gamma )} and E ( I γ ) = lim ε 0 E ε ( I γ ) {\displaystyle E(I\circ \gamma )=\lim _{\varepsilon \to 0}E_{\varepsilon }(I\circ \gamma )} {\displaystyle E(I\circ \gamma )=\lim _{\varepsilon \to 0}E_{\varepsilon }(I\circ \gamma )}. It is a short calculation (using the law of cosines) that the first terms transform correctly, i.e.,

    I ( γ ( u ) ) I ( γ ( v ) ) | I ( γ ( u ) ) I ( γ ( v ) ) | 2 = 1 | γ ( u ) γ ( v ) | 2 . {\displaystyle {\frac {\|I'(\gamma (u))\|\cdot \|I'(\gamma (v))\|}{|I(\gamma (u))-I(\gamma (v))|^{2}}}={\frac {1}{|\gamma (u)-\gamma (v)|^{2}}}.} {\displaystyle {\frac {\|I'(\gamma (u))\|\cdot \|I'(\gamma (v))\|}{|I(\gamma (u))-I(\gamma (v))|^{2}}}={\frac {1}{|\gamma (u)-\gamma (v)|^{2}}}.}

    Since u {\displaystyle u} {\displaystyle u} is arclength for γ {\displaystyle \gamma } {\displaystyle \gamma }, the regularization term of (1) is the elementary integral

    u = 0 [ 2 v = ε / 2 1 v 2 d v ] d u = 4 2 ε . {\displaystyle \int _{u=0}^{\ell }\left[2\int _{v=\varepsilon }^{\ell /2}{\frac {1}{v^{2}}}\,dv\right]\,du=4-{\frac {2\ell }{\varepsilon }}.} {\displaystyle \int _{u=0}^{\ell }\left[2\int _{v=\varepsilon }^{\ell /2}{\frac {1}{v^{2}}}\,dv\right]\,du=4-{\frac {2\ell }{\varepsilon }}.} 3

    Let s {\displaystyle s} {\displaystyle s} be an arclength parameter for I γ {\displaystyle I\circ \gamma } {\displaystyle I\circ \gamma }.
    Then d s ( u ) / d u = I ( γ ( u ) ) {\displaystyle ds(u)/du=\|I'(\gamma (u))\|} {\displaystyle ds(u)/du=\|I'(\gamma (u))\|} where I ( γ ( u ) ) = f ( u ) {\displaystyle \|I'(\gamma (u))\|=f(u)} {\displaystyle \|I'(\gamma (u))\|=f(u)} denotes the linear expansion factor of I {\displaystyle I’} {\displaystyle I'}. Since γ ( u ) {\displaystyle \gamma (u)} {\displaystyle \gamma (u)} is a Lipschitz function and I {\displaystyle I’} {\displaystyle I'} is smooth, f ( u ) {\displaystyle f(u)} {\displaystyle f(u)} is Lipschitz, hence, it has weak derivative f ( u ) L {\displaystyle f'(u)\in L^{\infty }} {\displaystyle f'(u)\in L^{\infty }}.

    r e g u l a r i z a t i o n ( 2 ) = u R / Z [ | v u | ε | ( I γ ) ( v ) | d v D ( I γ ( u ) , I γ ( v ) ) 2 ] | ( I γ ) ( u ) | d u = R / Z [ 4 L 1 ε + 1 ε ] d s , {\displaystyle {\begin{aligned}{\rm {{regularization}(2)=}}&\int _{u\in \mathbf {R} /\ell \mathbf {Z} }\left[\int _{|v-u|\geq \varepsilon }{\frac {|(I\circ \gamma )'(v)|\,dv}{D(I\circ \gamma (u),I\circ \gamma (v))^{2}}}\right]|(I\circ \gamma )'(u)|\,du\\=&\int _{\mathbf {R} /\ell \mathbf {Z} }\left[{\frac {4}{L}}-{\frac {1}{\varepsilon _{+}}}-{\frac {1}{\varepsilon _{-}}}\right]\,ds,\end{aligned}}} {\displaystyle {\begin{aligned}{\rm {{regularization}(2)=}}&\int _{u\in \mathbf {R} /\ell \mathbf {Z} }\left[\int _{|v-u|\geq \varepsilon }{\frac {|(I\circ \gamma )'(v)|\,dv}{D(I\circ \gamma (u),I\circ \gamma (v))^{2}}}\right]|(I\circ \gamma )'(u)|\,du\\=&\int _{\mathbf {R} /\ell \mathbf {Z} }\left[{\frac {4}{L}}-{\frac {1}{\varepsilon _{+}}}-{\frac {1}{\varepsilon _{-}}}\right]\,ds,\end{aligned}}} 4

    where L = L e n g t h ( I ( γ ) ) {\displaystyle L={\rm {{Length}(I(\gamma ))}}} {\displaystyle L={\rm {{Length}(I(\gamma ))}}} and

    ε + = ε + ( u ) = D ( ( I γ ) ( u ) , ( I γ ) ( u + ε ) ) = s ( u + ε ) s ( u ) = u u + ε f ( w ) d w = f ( u ) ε + ε 2 0 1 ( 1 t ) f ( u + ε t ) d t {\displaystyle {\begin{aligned}\varepsilon _{+}&=\varepsilon _{+}(u)=D((I\circ \gamma )(u),(I\circ \gamma )(u+\varepsilon ))=s(u+\varepsilon )-s(u)\\&=\int _{u}^{u+\varepsilon }f(w)\,dw=f(u)\varepsilon +\varepsilon ^{2}\int _{0}^{1}(1-t)f'(u+\varepsilon t)\,dt\end{aligned}}} {\displaystyle {\begin{aligned}\varepsilon _{+}&=\varepsilon _{+}(u)=D((I\circ \gamma )(u),(I\circ \gamma )(u+\varepsilon ))=s(u+\varepsilon )-s(u)\\&=\int _{u}^{u+\varepsilon }f(w)\,dw=f(u)\varepsilon +\varepsilon ^{2}\int _{0}^{1}(1-t)f'(u+\varepsilon t)\,dt\end{aligned}}}

    and

    ε = ε ( u ) = D ( ( I γ ) ( u ε ) , ( I γ ) ( u ) ) = f ( u ) ε ε 2 0 1 ( 1 t ) f ( u ε t ) d t . {\displaystyle \varepsilon _{-}=\varepsilon _{-}(u)=D((I\circ \gamma )(u-\varepsilon ),(I\circ \gamma )(u))=f(u)\varepsilon -\varepsilon ^{2}\int _{0}^{1}(1-t)f'(u-\varepsilon t)\,dt.} {\displaystyle \varepsilon _{-}=\varepsilon _{-}(u)=D((I\circ \gamma )(u-\varepsilon ),(I\circ \gamma )(u))=f(u)\varepsilon -\varepsilon ^{2}\int _{0}^{1}(1-t)f'(u-\varepsilon t)\,dt.}

    Since | f ( w ) | {\displaystyle |f'(w)|} {\displaystyle |f'(w)|} is uniformly bounded, we have

    1 ε + = 1 f ( u ) ε [ 1 + ε f ( u ) 0 1 ( 1 t ) f ( u + ε t ) d t ] 1 = 1 f ( u ) ε [ 1 ε f ( u ) 0 1 ( 1 t ) f ( u + ε t ) d t + O ( ε 2 ) ] = 1 f ( u ) ε 1 f ( u ) 2 0 1 ( 1 t ) f ( u + ε t ) d t + O ( ε ) . {\displaystyle {\begin{aligned}{\frac {1}{\varepsilon _{+}}}=&{\frac {1}{f(u)\varepsilon }}\left[{1+{\varepsilon \over f(u)}\int _{0}^{1}(1-t)f'(u+\varepsilon t)\,dt}\right]^{-1}\\=&{\frac {1}{f(u)\varepsilon }}\left[1-{\frac {\varepsilon }{f(u)}}\int _{0}^{1}(1-t)f'(u+\varepsilon t)\,dt+O(\varepsilon ^{2})\right]\\=&{\frac {1}{f(u)\varepsilon }}-{\frac {1}{f(u)^{2}}}\int _{0}^{1}(1-t)f'(u+\varepsilon t)\,dt+O(\varepsilon ).\end{aligned}}} {\displaystyle {\begin{aligned}{\frac {1}{\varepsilon _{+}}}=&{\frac {1}{f(u)\varepsilon }}\left[{1+{\varepsilon  \over f(u)}\int _{0}^{1}(1-t)f'(u+\varepsilon t)\,dt}\right]^{-1}\\=&{\frac {1}{f(u)\varepsilon }}\left[1-{\frac {\varepsilon }{f(u)}}\int _{0}^{1}(1-t)f'(u+\varepsilon t)\,dt+O(\varepsilon ^{2})\right]\\=&{\frac {1}{f(u)\varepsilon }}-{\frac {1}{f(u)^{2}}}\int _{0}^{1}(1-t)f'(u+\varepsilon t)\,dt+O(\varepsilon ).\end{aligned}}}

    Similarly,
    1 ε = 1 f ( u ) ε + 1 f ( u ) 2 0 1 ( 1 t ) f ( u ε t ) d t + O ( ε ) . {\displaystyle {\frac {1}{\varepsilon _{-}}}={\frac {1}{f(u)\varepsilon }}+{\frac {1}{f(u)^{2}}}\int _{0}^{1}(1-t)f'(u-\varepsilon t)\,dt+O(\varepsilon ).} {\displaystyle {\frac {1}{\varepsilon _{-}}}={\frac {1}{f(u)\varepsilon }}+{\frac {1}{f(u)^{2}}}\int _{0}^{1}(1-t)f'(u-\varepsilon t)\,dt+O(\varepsilon ).}

    Then by (4)

    r e g u l a r i z a t i o n   ( 2 ) = 4 0 2 ε d u + O ( ε ) + u = 0 t = 0 1 ( 1 t ) f ( u ) [ f ( u + ε t ) f ( u ε t ) ] d u d t = 4 2 ε + O ( ε ) . {\displaystyle {\begin{aligned}{\rm {{regularization}\ (2)=}}&4-\int _{0}^{\ell }{\frac {2}{\varepsilon }}\,du+O(\varepsilon )\\&+\int _{u=0}^{\ell }\int _{t=0}^{1}{\frac {(1-t)}{f(u)}}[f'(u+\varepsilon t)-f'(u-\varepsilon t)]\,du\,dt\\=&4-{\frac {2\ell }{\varepsilon }}+O(\varepsilon ).\end{aligned}}} {\displaystyle {\begin{aligned}{\rm {{regularization}\ (2)=}}&4-\int _{0}^{\ell }{\frac {2}{\varepsilon }}\,du+O(\varepsilon )\\&+\int _{u=0}^{\ell }\int _{t=0}^{1}{\frac {(1-t)}{f(u)}}[f'(u+\varepsilon t)-f'(u-\varepsilon t)]\,du\,dt\\=&4-{\frac {2\ell }{\varepsilon }}+O(\varepsilon ).\end{aligned}}} 5

    Comparing (3) and (5), we get
    E ε ( γ ) E ε ( I γ ) = O ( ε ) ; {\displaystyle E_{\varepsilon }(\gamma )-E_{\varepsilon }(I\circ \gamma )=O(\varepsilon );} {\displaystyle E_{\varepsilon }(\gamma )-E_{\varepsilon }(I\circ \gamma )=O(\varepsilon );}
    hence, E ( γ ) = E ( I γ ) {\displaystyle E(\gamma )=E(I\circ \gamma )} {\displaystyle E(\gamma )=E(I\circ \gamma )}.

    For the second assertion, let I {\displaystyle I} {\displaystyle I} send a point of γ {\displaystyle \gamma } {\displaystyle \gamma } to infinity. In this case L = {\displaystyle L=\infty } {\displaystyle L=\infty } and, thus, the constant term 4 in (5) disappears.

    Freedman–He–Wang conjecture

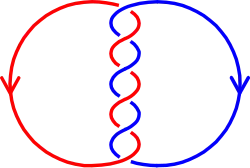
    The Freedman–He–Wang conjecture (1994) stated that the Möbius energy of nontrivial links in R 3 {\displaystyle \mathbb {R} ^{3}} {\displaystyle \mathbb {R} ^{3}} is minimized by the stereographic projection of the standard Hopf link. This was proved in 2012 by Ian Agol, Fernando C. Marques and André Neves, by using Almgren–Pitts min-max theory.[7] Let γ i : S 1 R 3 {\displaystyle \gamma _{i}:S^{1}\rightarrow \mathbb {R} ^{3}} {\displaystyle \gamma _{i}:S^{1}\rightarrow \mathbb {R} ^{3}}, i = 1 , 2 , {\displaystyle i=1,2,} {\displaystyle i=1,2,} be a link of 2 components, i.e., a pair of rectifiable closed curves in Euclidean three-space with γ 1 ( S 1 ) γ 2 ( S 1 ) = {\displaystyle \gamma _{1}(S^{1})\cap \gamma _{2}(S^{1})=\emptyset } {\displaystyle \gamma _{1}(S^{1})\cap \gamma _{2}(S^{1})=\emptyset }. The Möbius cross energy of the link ( γ 1 , γ 2 ) {\displaystyle (\gamma _{1},\gamma _{2})} {\displaystyle (\gamma _{1},\gamma _{2})} is defined to be

    E ( γ 1 , γ 2 ) = S 1 × S 1 | γ ˙ 1 ( s ) | | γ ˙ 2 ( t ) | | γ 1 ( s ) γ 2 ( t ) | 2 d s d t . {\displaystyle E(\gamma _{1},\gamma _{2})=\int _{S^{1}\times S^{1}}{\frac {|{\dot {\gamma }}_{1}(s)||{\dot {\gamma }}_{2}(t)|}{|\gamma _{1}(s)-\gamma _{2}(t)|^{2}}}\,ds\,dt.} {\displaystyle E(\gamma _{1},\gamma _{2})=\int _{S^{1}\times S^{1}}{\frac {|{\dot {\gamma }}_{1}(s)||{\dot {\gamma }}_{2}(t)|}{|\gamma _{1}(s)-\gamma _{2}(t)|^{2}}}\,ds\,dt.}

    The linking number of ( γ 1 , γ 2 ) {\displaystyle (\gamma _{1},\gamma _{2})} {\displaystyle (\gamma _{1},\gamma _{2})} is defined by letting

    l i n k ( γ 1 , γ 2 ) = 1 4 π γ 1 γ 2 r 1 r 2 | r 1 r 2 | 3 ( d r 1 × d r 2 ) = 1 4 π S 1 × S 1 d e t ( γ ˙ 1 ( s ) , γ ˙ 2 ( t ) , γ 1 ( s ) γ 2 ( t ) ) | γ 1 ( s ) γ 2 ( t ) | 3 d s d t . {\displaystyle {\begin{aligned}\mathrm {link} (\gamma _{1},\gamma _{2})&=\,{\frac {1}{4\pi }}\oint _{\gamma _{1}}\oint _{\gamma _{2}}{\frac {\mathbf {r} _{1}-\mathbf {r} _{2}}{|\mathbf {r} _{1}-\mathbf {r} _{2}|^{3}}}\cdot (d\mathbf {r} _{1}\times d\mathbf {r} _{2})\\&={\frac {1}{4\pi }}\int _{S^{1}\times S^{1}}{\frac {\mathrm {det} ({\dot {\gamma }}_{1}(s),{\dot {\gamma }}_{2}(t),\gamma _{1}(s)-\gamma _{2}(t))}{|\gamma _{1}(s)-\gamma _{2}(t)|^{3}}}\,ds\,dt.\end{aligned}}} {\displaystyle {\begin{aligned}\mathrm {link} (\gamma _{1},\gamma _{2})&=\,{\frac {1}{4\pi }}\oint _{\gamma _{1}}\oint _{\gamma _{2}}{\frac {\mathbf {r} _{1}-\mathbf {r} _{2}}{|\mathbf {r} _{1}-\mathbf {r} _{2}|^{3}}}\cdot (d\mathbf {r} _{1}\times d\mathbf {r} _{2})\\&={\frac {1}{4\pi }}\int _{S^{1}\times S^{1}}{\frac {\mathrm {det} ({\dot {\gamma }}_{1}(s),{\dot {\gamma }}_{2}(t),\gamma _{1}(s)-\gamma _{2}(t))}{|\gamma _{1}(s)-\gamma _{2}(t)|^{3}}}\,ds\,dt.\end{aligned}}}
    {\displaystyle \cdots } {\displaystyle \cdots } Möbius energy Möbius energy Möbius energy
    linking number −2 linking number −1 linking number 0
    Möbius energy Möbius energy Möbius energy {\displaystyle \cdots } {\displaystyle \cdots }
    linking number 1 linking number 2 linking number 3

    The numerator of the linking integrand contains a factor of the displacement between two line elements that reduces the cubic distance dependence to a square, similar to the Möbius energy integrand. The linking integrand will be reduced by the dot product of the displacement vector with the cross product of the two tangent vectors of those line elements, which may be unitary at a few locations but is typically less than one. For that reason, E ( γ 1 , γ 2 ) 4 π | l i n k ( γ 1 , γ 2 ) | {\displaystyle E(\gamma _{1},\gamma _{2})\geq 4\pi |{\rm {link}}(\gamma _{1},\gamma _{2})|} {\displaystyle E(\gamma _{1},\gamma _{2})\geq 4\pi |{\rm {link}}(\gamma _{1},\gamma _{2})|}. If two circles are unlinked and very far from each other, the cross energy can be made arbitrarily small but nonzero. If the linking number l i n k ( γ 1 , γ 2 ) {\displaystyle \mathrm {link} (\gamma _{1},\gamma _{2})} {\displaystyle \mathrm {link} (\gamma _{1},\gamma _{2})} is non-zero, the link is called non-split and for the non-split link, E ( γ 1 , γ 2 ) 4 π {\displaystyle E(\gamma _{1},\gamma _{2})\geq 4\pi } {\displaystyle E(\gamma _{1},\gamma _{2})\geq 4\pi }. So we are interested in the minimal energy of non-split links.
    Note that the definition of the energy extends
    to any 2-component link in R n {\displaystyle \mathbb {R} ^{n}} {\displaystyle \mathbb {R} ^{n}}. The Möbius energy has the remarkable property of being invariant under conformal transformations of R 3 {\displaystyle \mathbb {R} ^{3}} {\displaystyle \mathbb {R} ^{3}}. This property is explained as follows. Let F : R 3 S 3 {\displaystyle F:\mathbb {R} ^{3}\rightarrow {S^{3}}} {\displaystyle F:\mathbb {R} ^{3}\rightarrow {S^{3}}} denote a conformal map. Then E ( γ 1 , γ 2 ) = E ( F γ 1 , F γ 2 ) . {\displaystyle E(\gamma _{1},\gamma _{2})=E(F\circ \gamma _{1},F\circ \gamma _{2}).} {\displaystyle E(\gamma _{1},\gamma _{2})=E(F\circ \gamma _{1},F\circ \gamma _{2}).} This condition is called the conformal invariance property of the Möbius cross energy.

    Main Theorem. Let γ i : S 1 R 3 {\displaystyle \gamma _{i}:S^{1}\rightarrow \mathbb {R} ^{3}} {\displaystyle \gamma _{i}:S^{1}\rightarrow \mathbb {R} ^{3}}, i = 1 , 2 , {\displaystyle i=1,2,} {\displaystyle i=1,2,} be a non-split link of 2 components link. Then E ( γ 1 , γ 2 ) 2 π 2 {\displaystyle E(\gamma _{1},\gamma _{2})\geq 2\pi ^{2}} {\displaystyle E(\gamma _{1},\gamma _{2})\geq 2\pi ^{2}}.
    Moreover, if E ( γ 1 , γ 2 ) = 2 π 2 {\displaystyle E(\gamma _{1},\gamma _{2})=2\pi ^{2}} {\displaystyle E(\gamma _{1},\gamma _{2})=2\pi ^{2}} then there exists a conformal map F : R 3 S 3 {\displaystyle F:\mathbb {R} ^{3}\rightarrow {S^{3}}} {\displaystyle F:\mathbb {R} ^{3}\rightarrow {S^{3}}} such that F γ 1 ( t ) = ( cos t , sin t , 0 , 0 ) {\displaystyle F\circ \gamma _{1}(t)=(\cos t,\sin t,0,0)} {\displaystyle F\circ \gamma _{1}(t)=(\cos t,\sin t,0,0)} and F γ 2 ( t ) = ( 0 , 0 , cos t , sin t ) {\displaystyle F\circ \gamma _{2}(t)=(0,0,\cos t,\sin t)} {\displaystyle F\circ \gamma _{2}(t)=(0,0,\cos t,\sin t)} (the standard Hopf link up to orientation and reparameterization).

    Given two non-intersecting differentiable curves γ 1 , γ 2 : S 1 R 3 {\displaystyle \gamma _{1},\gamma _{2}\colon S^{1}\rightarrow \mathbb {R} ^{3}} {\displaystyle \gamma _{1},\gamma _{2}\colon S^{1}\rightarrow \mathbb {R} ^{3}}, define the Gauss map Γ {\displaystyle \Gamma } {\displaystyle \Gamma } from the torus to the sphere by

    Γ ( s , t ) = γ 1 ( s ) γ 2 ( t ) | γ 1 ( s ) γ 2 ( t ) | . {\displaystyle \Gamma (s,t)={\frac {\gamma _{1}(s)-\gamma _{2}(t)}{|\gamma _{1}(s)-\gamma _{2}(t)|}}.} {\displaystyle \Gamma (s,t)={\frac {\gamma _{1}(s)-\gamma _{2}(t)}{|\gamma _{1}(s)-\gamma _{2}(t)|}}.}

    The Gauss map of a link ( γ 1 , γ 2 ) {\displaystyle (\gamma _{1},\gamma _{2})} {\displaystyle (\gamma _{1},\gamma _{2})} in R 4 {\displaystyle \mathbf {R} ^{4}} {\displaystyle \mathbf {R} ^{4}}, denoted by g = G ( γ 1 , γ 2 ) {\displaystyle g=G(\gamma _{1},\gamma _{2})} {\displaystyle g=G(\gamma _{1},\gamma _{2})}, is the Lipschitz map g : S 1 × S 1 S 3 {\displaystyle g:S^{1}\times S^{1}\to S^{3}} {\displaystyle g:S^{1}\times S^{1}\to S^{3}} defined by
    g ( s , t ) = γ 1 ( s ) γ 2 ( t ) | γ 1 ( s ) γ 2 ( t ) | . {\displaystyle g(s,t)={\frac {\gamma _{1}(s)-\gamma _{2}(t)}{|\gamma _{1}(s)-\gamma _{2}(t)|}}.} {\displaystyle g(s,t)={\frac {\gamma _{1}(s)-\gamma _{2}(t)}{|\gamma _{1}(s)-\gamma _{2}(t)|}}.}
    We denote an open ball in R 4 {\displaystyle \mathbf {R} ^{4}} {\displaystyle \mathbf {R} ^{4}}, centered at x {\displaystyle \mathbf {x} } {\displaystyle \mathbf {x} } with radius r {\displaystyle r} {\displaystyle r}, by B r 4 ( x ) {\displaystyle B_{r}^{4}(\mathbf {x} )} {\displaystyle B_{r}^{4}(\mathbf {x} )}. The boundary of this ball is denoted by S r 3 ( x ) {\displaystyle S_{r}^{3}(\mathbf {x} )} {\displaystyle S_{r}^{3}(\mathbf {x} )}. An intrinsic open ball of S 3 {\displaystyle S^{3}} {\displaystyle S^{3}}, centered at p S 3 {\displaystyle \mathbf {p} \in S^{3}} {\displaystyle \mathbf {p} \in S^{3}} with radius r {\displaystyle r} {\displaystyle r}, is denoted by B r ( p ) {\displaystyle B_{r}(\mathbf {p} )} {\displaystyle B_{r}(\mathbf {p} )}.
    We have

    g s = γ ˙ 1 g , γ ˙ 1 g | γ 1 γ 2 | and g t = γ ˙ 2 g , γ ˙ 2 g | γ 1 γ 2 | . {\displaystyle {\frac {\partial g}{\partial s}}={{\dot {\gamma }}_{1}-\langle g,{\dot {\gamma }}_{1}\rangle g \over |\gamma _{1}-\gamma _{2}|}\quad {\mbox{and}}\quad {\frac {\partial g}{\partial t}}=-{{\dot {\gamma }}_{2}-\langle g,{\dot {\gamma }}_{2}\rangle g \over |\gamma _{1}-\gamma _{2}|}.} {\displaystyle {\frac {\partial g}{\partial s}}={{\dot {\gamma }}_{1}-\langle g,{\dot {\gamma }}_{1}\rangle g \over |\gamma _{1}-\gamma _{2}|}\quad {\mbox{and}}\quad {\frac {\partial g}{\partial t}}=-{{\dot {\gamma }}_{2}-\langle g,{\dot {\gamma }}_{2}\rangle g \over |\gamma _{1}-\gamma _{2}|}.}

    Thus,

    | g s | 2 | g t | 2 g s , g t 2 | g s | 2 | g t | 2 = | γ ˙ 1 | 2 g , γ ˙ 1 2 | γ 1 γ 2 | 2 | γ ˙ 2 | 2 g , γ ˙ 2 2 | γ 1 γ 2 | 2 | γ ˙ 1 | 2 | γ ˙ 2 | 2 | γ 1 γ 2 | 4 . {\displaystyle {\begin{aligned}\left|{\frac {\partial g}{\partial s}}\right|^{2}\left|{\frac {\partial g}{\partial t}}\right|^{2}-\left\langle {\frac {\partial g}{\partial s}},{\frac {\partial g}{\partial t}}\right\rangle ^{2}&\leq \left|{\frac {\partial g}{\partial s}}\right|^{2}\left|{\frac {\partial g}{\partial t}}\right|^{2}\\&={\frac {|{\dot {\gamma }}_{1}|^{2}-\langle g,{\dot {\gamma }}_{1}\rangle ^{2}}{|\gamma _{1}-\gamma _{2}|^{2}}}{\frac {|{\dot {\gamma }}_{2}|^{2}-\langle g,{\dot {\gamma }}_{2}\rangle ^{2}}{|\gamma _{1}-\gamma _{2}|^{2}}}\\&\leq {\frac {|{\dot {\gamma }}_{1}|^{2}|{\dot {\gamma }}_{2}|^{2}}{|\gamma _{1}-\gamma _{2}|^{4}}}.\end{aligned}}} {\displaystyle {\begin{aligned}\left|{\frac {\partial g}{\partial s}}\right|^{2}\left|{\frac {\partial g}{\partial t}}\right|^{2}-\left\langle {\frac {\partial g}{\partial s}},{\frac {\partial g}{\partial t}}\right\rangle ^{2}&\leq \left|{\frac {\partial g}{\partial s}}\right|^{2}\left|{\frac {\partial g}{\partial t}}\right|^{2}\\&={\frac {|{\dot {\gamma }}_{1}|^{2}-\langle g,{\dot {\gamma }}_{1}\rangle ^{2}}{|\gamma _{1}-\gamma _{2}|^{2}}}{\frac {|{\dot {\gamma }}_{2}|^{2}-\langle g,{\dot {\gamma }}_{2}\rangle ^{2}}{|\gamma _{1}-\gamma _{2}|^{2}}}\\&\leq {\frac {|{\dot {\gamma }}_{1}|^{2}|{\dot {\gamma }}_{2}|^{2}}{|\gamma _{1}-\gamma _{2}|^{4}}}.\end{aligned}}}

    It follows that for almost every ( s , t ) S 1 × S 1 {\displaystyle (s,t)\in S^{1}\times S^{1}} {\displaystyle (s,t)\in S^{1}\times S^{1}},
    | J a c g | ( s , t ) | γ ˙ 1 ( s ) | | γ ˙ 2 ( t ) | | γ 1 ( s ) γ 2 ( t ) | 2 . {\displaystyle |{\rm {Jac\,}}g|(s,t)\leq {\frac {|{\dot {\gamma }}_{1}(s)||{\dot {\gamma }}_{2}(t)|}{|\gamma _{1}(s)-\gamma _{2}(t)|^{2}}}.} {\displaystyle |{\rm {Jac\,}}g|(s,t)\leq {\frac {|{\dot {\gamma }}_{1}(s)||{\dot {\gamma }}_{2}(t)|}{|\gamma _{1}(s)-\gamma _{2}(t)|^{2}}}.}
    If equality holds at ( s , t ) {\displaystyle (s,t)} {\displaystyle (s,t)}, then
    γ ˙ 1 ( s ) , γ ˙ 2 ( t ) = γ ˙ 1 ( s ) , γ 1 ( s ) γ 2 ( t ) = γ ˙ 2 ( t ) , γ 1 ( s ) γ 2 ( t ) = 0. {\displaystyle \langle {\dot {\gamma }}_{1}(s),{\dot {\gamma }}_{2}(t)\rangle =\langle {\dot {\gamma }}_{1}(s),\gamma _{1}(s)-\gamma _{2}(t)\rangle =\langle {\dot {\gamma }}_{2}(t),\gamma _{1}(s)-\gamma _{2}(t)\rangle =0.} {\displaystyle \langle {\dot {\gamma }}_{1}(s),{\dot {\gamma }}_{2}(t)\rangle =\langle {\dot {\gamma }}_{1}(s),\gamma _{1}(s)-\gamma _{2}(t)\rangle =\langle {\dot {\gamma }}_{2}(t),\gamma _{1}(s)-\gamma _{2}(t)\rangle =0.}

    M ( C ) S 1 × S 1 | J a c g | d s d t E ( γ 1 , γ 2 ) . {\displaystyle {\mathbf {M} }(C)\leq \int _{S^{1}\times S^{1}}|{\rm {Jac\,}}g|\,ds\,dt\leq E(\gamma _{1},\gamma _{2}).} {\displaystyle {\mathbf {M} }(C)\leq \int _{S^{1}\times S^{1}}|{\rm {Jac\,}}g|\,ds\,dt\leq E(\gamma _{1},\gamma _{2}).}

    If the link ( γ 1 , γ 2 ) {\displaystyle (\gamma _{1},\gamma _{2})} {\displaystyle (\gamma _{1},\gamma _{2})} is contained in an oriented affine hyperplane with unit normal vector p S 3 {\displaystyle \mathbf {p} \in S^{3}} {\displaystyle \mathbf {p} \in S^{3}} compatible with the orientation, then C = l i n k ( γ 1 , γ 2 ) B π / 2 ( p ) . {\displaystyle C={\rm {link}}(\gamma _{1},\gamma _{2})\cdot \partial B_{\pi /2}(-\mathbf {p} ).} {\displaystyle C={\rm {link}}(\gamma _{1},\gamma _{2})\cdot \partial B_{\pi /2}(-\mathbf {p} ).}

    References

    • Adams, Colin (2004). The Knot Book: An Elementary Introduction to the Mathematical Theory of Knots. American Mathematical Society. ISBN 9780821836781.
    • Hass, Joel (April–May 1998). “Algorithms for recognizing knots and 3-manifolds”. Chaos, Solitons and Fractals. 9 (4–5): 569–581. arXiv:math/9712269. Bibcode:1998CSF…..9..569H. doi:10.1016/S0960-0779(97)00109-4. S2CID 7381505.
    • Sossinsky, Alexei (2002). Knots, mathematics with a twist. Harvard University Press. ISBN 9780674009448.

    Footnotes

    1. O’Hara, Jun (1991). “Energy of a knot”. Topology. 30 (2): 241–247. doi:10.1016/0040-9383(91)90010-2. MR 1098918.
    2. Kim, Denise; Kusner, Rob (1993). “Torus knots extremizing the Möbius energy”. Experimental Mathematics. 2 (1): 1–9. doi:10.1080/10586458.1993.10504264. MR 1246479.
    3. Freedman, Michael H.; He, Zheng-Xu; Wang, Zhenghan (January 1994). “Möbius energy of knots and unknots”. Annals of Mathematics. Second Series. 139 (1): 1–50. doi:10.2307/2946626. JSTOR 2946626. MR 1259363.
    4. Adams 2004; Sossinsky 2002.
    5. 1 2 Hass 1998.
    6. Hoste, Jim (December 2005). “The enumeration and classification of knots and links”. In William W. Menasco; Morwen B. Thistlethwaite (eds.). Handbook of Knot Theory (PDF). Amsterdam: Elsevier. pp. 209–232. doi:10.1016/B978-044451452-3/50006-X. ISBN 9780444514523.
    7. Agol, Ian; Marques, Fernando C.; Neves, André (2012). “Min-max theory and the energy of links”. arXiv:1205.0825 [math.GT].


    This article is adapted from “Möbius energy” on Wikipedia, written by its contributors, and used under CC BY-SA 4.0. Text on this page is available under the same licence. Source snapshot: Wikipedia via Kiwix, 2026-07-20.
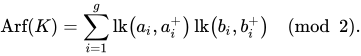
  • Anchor bend

    Anchor bend
    Anchor bend
    Names Anchor bend, fisherman’s bend
    Category Hitch
    Related Round turn and two half hitches
    Releasing Jamming
    Typical use attaching a rope to a ring or similar termination
    ABoK #24, #1518, #1722 – #1724, #1840 – #1842

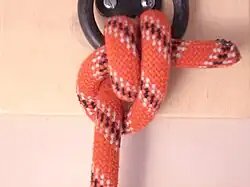
    The anchor bend is a knot used for attaching a rope to a ring or similar termination. The name is a misnomer, as it is technically not a bend, but a hitch.

    Origins

    Anchor bend
    “oncear bendum,” an early evidence of use of anchor bends by Anglo-Saxons from Beowulf

    Its name originates from the time when “bend” was understood to simply mean “tie to”; today, a bend strictly refers to a knot that joins two lines.

    Techniques

    While the knot can become jammed in some modern materials, it is usually easily untied after moderate loads; it can be made more resistant to jamming by taking an extra turn around the object—this will make for a one-diameter longer span of the end to reach around the standing part to be tucked (although in a case of tying to a small shackle or link of a chain, this might not be possible). It is the accepted knot for attaching anchors (or more usually anchor chains) to warps. The knot is very similar to a round turn and two half hitches except that the first half hitch is passed under the turn. In many everyday uses, the finishing half-hitch need not be made; alternatively, one might seek surer security by tying off the end with a strangle knot to the standing part.

    Anchor bend
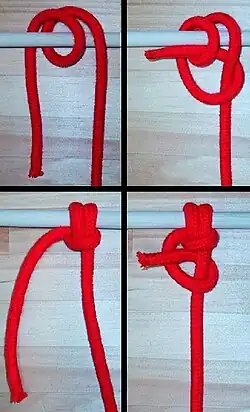
    Anchor bend step by step, with a finishing half hitch.

    See also

    External links


    This article is adapted from “Anchor bend” on Wikipedia, written by its contributors, and used under CC BY-SA 4.0. Text on this page is available under the same licence. Source snapshot: Wikipedia via Kiwix, 2026-07-20.

  • Ménage problem

    Ménage problem
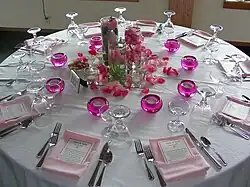
    A table with ten place settings. There are 3120 different ways in which five male-female couples can sit at this table such that men and women alternate and nobody sits next to their partner.

    In combinatorial mathematics, the ménage problem or problème des ménages asks for the number of different ways in which it is possible to seat a set of male-female couples at a round dining table so that men and women alternate and nobody sits next to his or her partner. (Ménage is the French word for “household”, referring here to a male-female couple.) This problem was formulated in 1891 by Édouard Lucas and independently, a few years earlier, by Peter Guthrie Tait in connection with knot theory.[1] For a number of couples equal to 3, 4, 5, … the number of seating arrangements is

    12, 96, 3120, 115200, 5836320, 382072320, 31488549120, … (sequence A059375 in the OEIS).

    Mathematicians have developed formulas and recurrence equations for computing these numbers and related sequences of numbers. Along with their applications to etiquette and knot theory, these numbers also have a graph theoretic interpretation: they count the numbers of matchings and Hamiltonian cycles in certain families of graphs.

    Touchard’s formula

    Let Mn denote the number of seating arrangements for n couples. Touchard (1934) derived the formula

    M n = 2 n ! k = 0 n ( 1 ) k 2 n 2 n k ( 2 n k k ) ( n k ) ! . {\displaystyle M_{n}=2\cdot n!\sum _{k=0}^{n}(-1)^{k}{\frac {2n}{2n-k}}{2n-k \choose k}(n-k)!.} {\displaystyle M_{n}=2\cdot n!\sum _{k=0}^{n}(-1)^{k}{\frac {2n}{2n-k}}{2n-k \choose k}(n-k)!.}

    Much subsequent work has gone into alternative proofs for this formula and into various generalized versions of the problem.

    A different umbral formula for Mn involving Chebyshev polynomials of first kind was given by Wyman & Moser (1958).

    Ménage numbers and ladies-first solutions

    There are 2×n! ways of seating the women: there are two sets of seats that can be arranged for the women, and there are n! ways of seating them at a particular set of seats. For each seating arrangement for the women, there are

    A n = k = 0 n ( 1 ) k 2 n 2 n k ( 2 n k k ) ( n k ) ! {\displaystyle A_{n}=\sum _{k=0}^{n}(-1)^{k}{\frac {2n}{2n-k}}{2n-k \choose k}(n-k)!} {\displaystyle A_{n}=\sum _{k=0}^{n}(-1)^{k}{\frac {2n}{2n-k}}{2n-k \choose k}(n-k)!}

    ways of seating the men; this formula simply omits the 2×n! factor from Touchard’s formula. The resulting smaller numbers (again, starting from n = 3),

    1, 2, 13, 80, 579, 4738, 43387, 439792, … (sequence A000179 in the OEIS)

    are called the ménage numbers. The factor 2 n 2 n k ( 2 n k k ) {\displaystyle {\frac {2n}{2n-k}}{2n-k \choose k}} {\displaystyle {\frac {2n}{2n-k}}{2n-k \choose k}} is the number of ways of forming k non-overlapping pairs of adjacent seats or, equivalently, the number of matchings of k edges in a cycle graph of 2n vertices. The expression for An is the immediate result of applying the principle of inclusion–exclusion to arrangements in which the people seated at the endpoints of each edge of a matching are required to be a couple.

    Until the work of Bogart & Doyle (1986), solutions to the ménage problem took the form of first finding all seating arrangements for the women and then counting, for each of these partial seating arrangements, the number of ways of completing it by seating the men away from their partners. Bogart and Doyle argued that Touchard’s formula may be derived directly by considering all seating arrangements at once rather than by factoring out the participation of the women.[2] However, Kirousis & Kontogeorgiou (2018) found the even more straightforward ladies-first solution described above by making use of a few of Bogart and Doyle’s ideas (although they took care to recast the argument in non-gendered language).

    The ménage numbers satisfy the recurrence relation[3]

    A n = n A n 1 + n n 2 A n 2 + 4 ( 1 ) n 1 n 2 {\displaystyle A_{n}=nA_{n-1}+{\frac {n}{n-2}}A_{n-2}+{\frac {4(-1)^{n-1}}{n-2}}} {\displaystyle A_{n}=nA_{n-1}+{\frac {n}{n-2}}A_{n-2}+{\frac {4(-1)^{n-1}}{n-2}}}

    and the simpler four-term recurrence[4]

    A n = n A n 1 + 2 A n 2 ( n 4 ) A n 3 A n 4 , {\displaystyle \displaystyle A_{n}=nA_{n-1}+2A_{n-2}-(n-4)A_{n-3}-A_{n-4},} {\displaystyle \displaystyle A_{n}=nA_{n-1}+2A_{n-2}-(n-4)A_{n-3}-A_{n-4},}

    from which the ménage numbers themselves can easily be calculated.

    Graph-theoretical interpretations

    Ménage problem
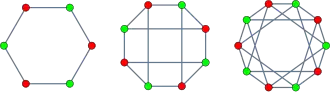
    Crown graphs with six, eight, and ten vertices. The outer cycle of each graph forms a Hamiltonian cycle; the eight and ten vertex graphs also have other Hamiltonian cycles.

    Solutions to the ménage problem may be interpreted in graph-theoretic terms, as directed Hamiltonian cycles in crown graphs. A crown graph is formed by removing a perfect matching from a complete bipartite graph Kn,n; it has 2n vertices of two colors, and each vertex of one color is connected to all but one of the vertices of the other color. In the case of the ménage problem, the vertices of the graph represent men and women, and the edges represent pairs of men and women who are allowed to sit next to each other. This graph is formed by removing the perfect matching formed by the male-female couples from a complete bipartite graph that connects every man to every woman. Any valid seating arrangement can be described by the sequence of people in order around the table, which forms a Hamiltonian cycle in the graph. However, two Hamiltonian cycles are considered to be equivalent if they connect the same vertices in the same cyclic order regardless of the starting vertex, while in the ménage problem the starting position is considered significant: if, as in Alice’s tea party, all the guests shift their positions by one seat, it is considered a different seating arrangement even though it is described by the same cycle. Therefore, the number of oriented Hamiltonian cycles in a crown graph is smaller by a factor of 2n than the number of seating arrangements,[5] but larger by a factor of (n  1)! than the ménage numbers. The sequence of numbers of cycles in these graphs (as before, starting at n = 3) is

    2, 12, 312, 9600, 416880, 23879520, 1749363840, … (sequence A094047 in the OEIS).

    A second graph-theoretic description of the problem is also possible. Once the women have been seated, the possible seating arrangements for the remaining men can be described as perfect matchings in a graph formed by removing a single Hamiltonian cycle from a complete bipartite graph; the graph has edges connecting open seats to men, and the removal of the cycle corresponds to forbidding the men to sit in either of the open seats adjacent to their wives. The problem of counting matchings in a bipartite graph, and therefore a fortiori the problem of computing ménage numbers, can be solved using the permanents of certain 0-1 matrices. In the case of the ménage problem, the matrix arising from this view of the problem is the circulant matrix in which all but two adjacent elements of the generating row equal 1.[6]

    Knot theory

    Tait’s motivation for studying the ménage problem came from trying to find a complete listing of mathematical knots with a given number of crossings, say n. In Dowker notation for knot diagrams, an early form of which was used by Tait, the 2n points where a knot crosses itself, in consecutive order along the knot, are labeled with the 2n numbers from 1 to 2n. In a reduced diagram, the two labels at a crossing cannot be consecutive, so the set of pairs of labels at each crossing, used in Dowker notation to represent the knot, can be interpreted as a perfect matching in a graph that has a vertex for every number in the range from 1 to 2n and an edge between every pair of numbers that has different parity and are non-consecutive modulo 2n. This graph is formed by removing a Hamiltonian cycle (connecting consecutive numbers) from a complete bipartite graph (connecting all pairs of numbers with different parity), and so it has a number of matchings equal to a ménage number. For alternating knots, this matching is enough to describe the knot diagram itself; for other knots, an additional positive or negative sign needs to be specified for each crossing pair to determine which of the two strands of the crossing lies above the other strand.

    However, the knot listing problem has some additional symmetries not present in the ménage problem: one obtains different Dowker notations for the same knot diagram if one begins the labeling at a different crossing point, and these different notations should all be counted as representing the same diagram. For this reason, two matchings that differ from each other by a cyclic permutation should be treated as equivalent and counted only once. Gilbert (1956) solved this modified enumeration problem, showing that the number of different matchings is

    1, 2, 5, 20, 87, 616, 4843, 44128, 444621, … (sequence A002484 in the OEIS).

    See also

    • Oberwolfach problem, a different mathematical problem involving the arrangement of diners at tables
    • Problème des rencontres, a similar problem involving partial derangements

    Notes

    References

    External links


    This article is adapted from “Ménage problem” on Wikipedia, written by its contributors, and used under CC BY-SA 4.0. Text on this page is available under the same licence. Source snapshot: Wikipedia via Kiwix, 2026-07-20.

  • Alternating planar algebra

    The concept of alternating planar algebras first appeared in the work of Hernando Burgos-Soto[1] on the Jones polynomial of alternating tangles. Alternating planar algebras provide an appropriate algebraic framework for other knot invariants in cases the elements involved in the computation are alternating. The concept has been used in extending to tangles some properties of Jones polynomial and Khovanov homology of alternating links.

    Definition

    An alternating planar algebra is an oriented planar algebra, where the d {\displaystyle d} {\displaystyle d}-input planar arc diagrams D {\displaystyle D} {\displaystyle D} satisfy the following conditions:

    • The number k {\displaystyle k} {\displaystyle k} of strings ending on the external boundary of D {\displaystyle D} {\displaystyle D} is greater than 0.
    • There is complete connection among input discs of the diagram and its arcs, namely, the union of the diagram arcs and the boundary of the internal holes is a connected set.
    • The in- and out-strings alternate in every boundary component of the diagram.

    A planar arc diagram like this has been denominated type- A {\displaystyle A} {\displaystyle A} planar diagram.

    Applications

    There are two known applications of the concept of alternating planar algebra.

    • It was used for extend to tangles the property that states that the Jones Polynomial of an alternating link is an alternating polynomial.
    • It was used for extend to tangles a result about the Khovanov homology that states that The Khovanov homology of an alternating link is supported in two lines.[2]

    Notes

    1. Burgos-Soto, Hernando (2010). “The Jones Polynomial of Alternating Tangles”. Journal of Knot Theory and Its Ramifications. 19 (11): 1487–1505. arXiv:0807.2600. doi:10.1142/s0218216510008510. S2CID 13993750.
    2. Bar-Natan, Dror; Burgos-Soto, Hernando (2014). “Khovanov homology for alternating tangles”. Journal of Knot Theory and Its Ramifications. 23 (2): 1450013. arXiv:1305.1695. doi:10.1142/s0218216514500138. S2CID 119237571.

    This article is adapted from “Alternating planar algebra” on Wikipedia, written by its contributors, and used under CC BY-SA 4.0. Text on this page is available under the same licence. Source snapshot: Wikipedia via Kiwix, 2026-07-20.